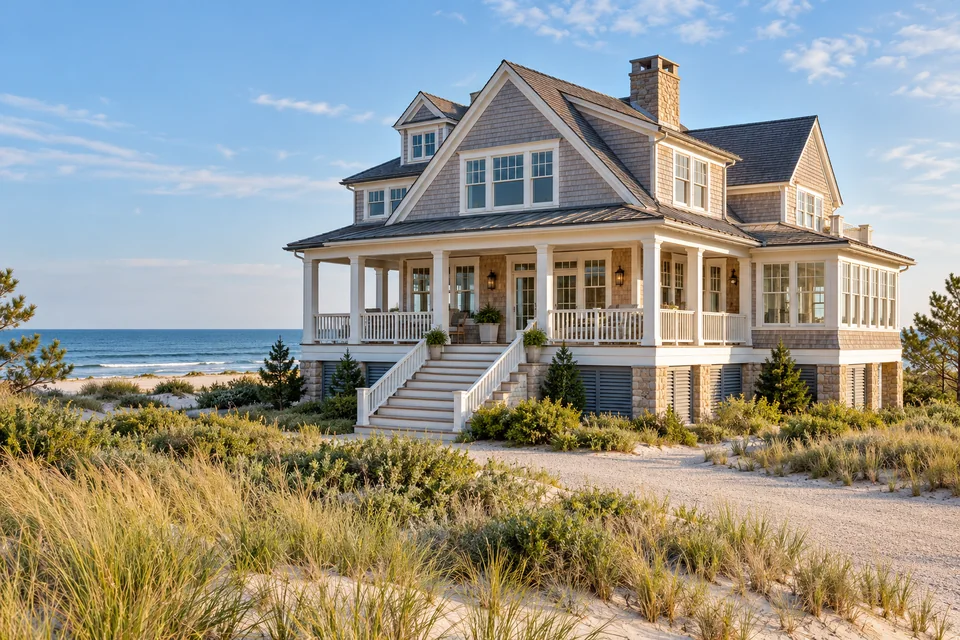
Coastal, with details to coordinate
Wind, flood, deductibles, and the cost to rebuild.
Explore coastal homesDistinctive homes. Individual attention.
From custom details and valued collections to coastal exposure or a non-renewal, start with what makes your home different.
For estimated reconstruction costs of $750,000 and up. Not sure of yours? We can start with what you know.
For distinctive homes and what is inside.
Coastal, historic, wildfire, and non-renewals.
Other homes, valuables, vehicles, and liability.
A starting point that fits you
A better fit. A change in plans. A home that needs a closer look. Choose a starting point, or go straight to requesting a quote.
More than one concern? You can include the rest in the next step.
Homes are not all alike
Wind, flood, deductibles, and the cost to rebuild.
Explore coastal homes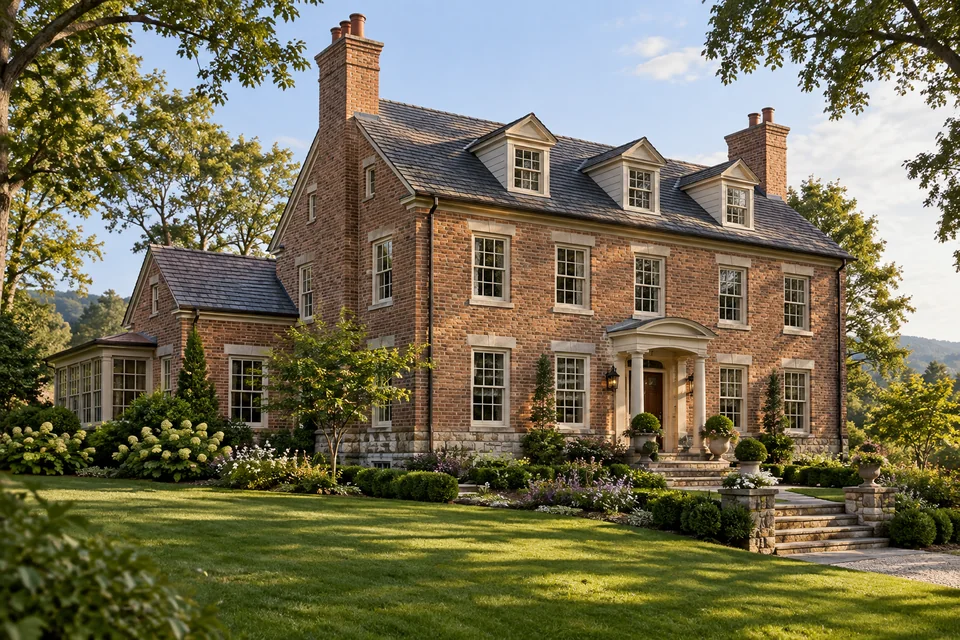
Original materials, older systems, and specialist restoration.
Explore historic homes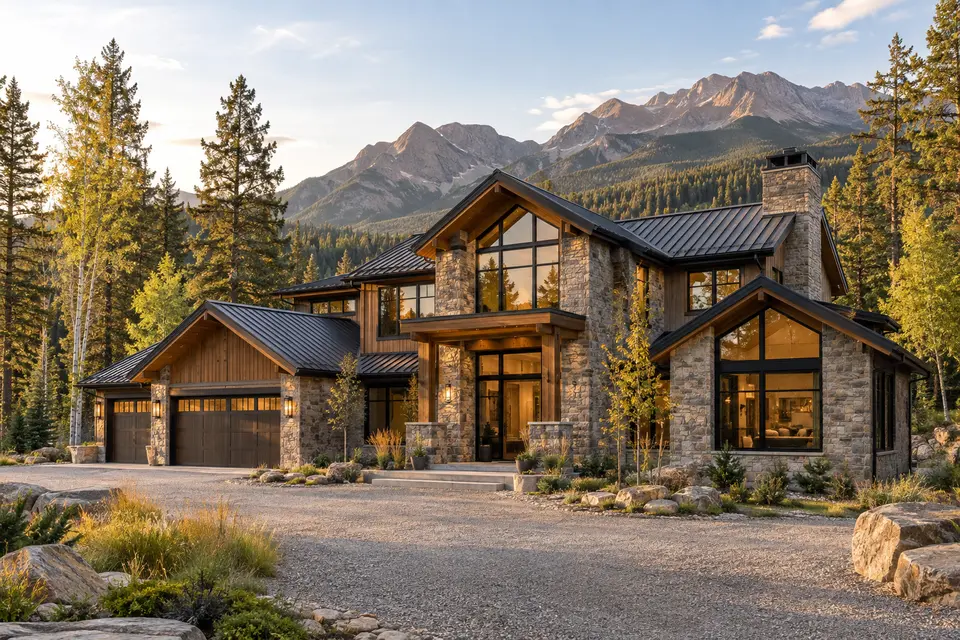
Wildfire exposure, access, and the improvements already made.
Explore wildfire considerations
Seasonal use, water protection, guests, and time away.
Explore second homes
An addition, restoration, or move-out during major work.
Explore renovation coverage
Detailed rebuilding estimates and questions about water damage.
Explore water damage coverageMore than one concern? Explore historic homes with wildfire exposure, or find guidance for complex homes. Images are illustrative, not customer properties.
Beyond the exterior
Original millwork. Custom cabinetry. A collection built over years. A useful insurance review starts with what would need attention if it had to be repaired or replaced.
Understand reconstruction cost and review valuables and collections as related, but distinct, questions.
Discuss my home and householdA clear starting point
Tell us how you use the home, what brought you here, and whether a deadline is approaching. You do not need every document ready.
A specialist can clarify the details and information needed to explore potential options. Mention other homes, vehicles, valuables, and liability needs too.
When quotes are available, compare coverage, deductibles, limitations, and price. A request does not bind coverage or guarantee placement.
Situations, made clearer
Original finishes and an older roof call for different questions. Start with the notice, then bring restoration needs and completed updates into the same review.
See the questions to organizeHow often you visit is only part of the picture. Repairs, monitoring, and how the home is cared for while empty deserve attention too.
See the questions to organizeHypothetical examples, not customer outcomes or coverage promises.
The reading room
Your home, properly understood
Understand reconstruction cost, market value, replacement cost coverage, and the details that matter when insuring a distinctive high-value home.
Read the guideBeyond ordinary contents
Review insurance for jewelry, fine art, and collections, including special limits, appraisal records, settlement terms, and coverage away from home.
Read the guideRenovations and construction
Plan insurance for a high-value home renovation, addition, or new build. Review construction coverage, occupancy changes, contractors, and completed value.
Read the guideA clear next step
Facing a high-value home insurance non-renewal? Learn what to gather, what to compare, and how to explore replacement coverage before your deadline.
Read the guideQuestions, answered
Our service focuses on homes with estimated reconstruction costs of $750,000 or more. That is a starting point for discussing your needs, not a universal insurer eligibility rule. A home’s purchase price, land value, and mortgage balance do not by themselves establish its reconstruction cost.
Yes, non-renewals and complex properties are part of our specialty. The available options depend on the reason for the notice, the home, its location, and underwriting. Keep the notice and current policy available, and tell us the date your coverage is scheduled to end.
Yes, the conversation can include additional residences, valuables, flood, and personal liability needs. Tell us about your household as well as the home you are contacting us about. The resulting solution may involve more than one policy or insurer.
We welcome inquiries involving coastal homes, historic properties, and other unusual insurance needs. Construction details, maintenance, occupancy, and hazard exposure all matter. A property review is needed before specific options or terms can be determined.
We offer assistance in 46 states. Services are not offered in California, Hawaii, New York, or Rhode Island. Being in a served state does not mean every property or coverage request is eligible.
No, requesting a quote does not bind, renew, or change insurance. Coverage begins only when the required application, underwriting, payment, and binding steps have been completed and confirmed. Ask for written confirmation of the effective date and terms before relying on a new policy.
Start with the property, what matters to you, and any deadline. We can discuss the home alone or the household around it.